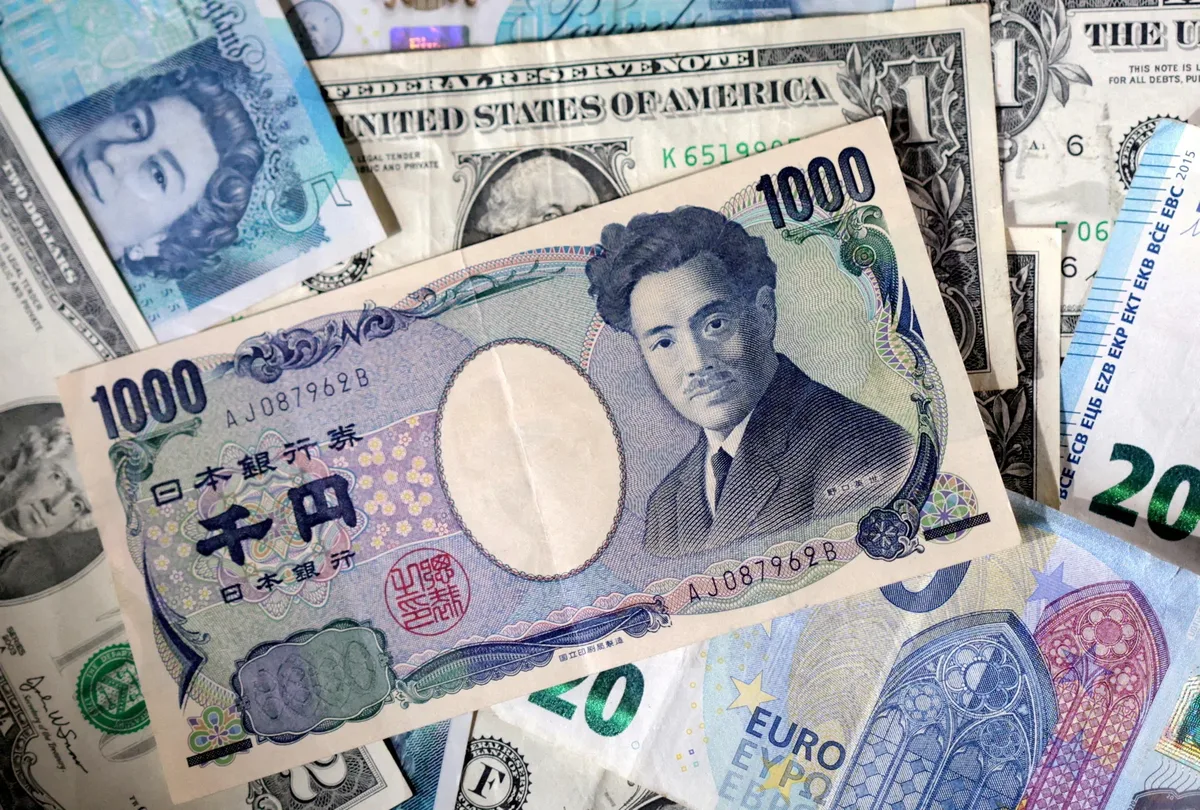
The US dollar index fell 0.2% to 99.23 on June 5, retreating from a two-month high of 99.56 reached the previous day amid mixed market reactions to economic data and geopolitical events [1]. The Japanese yen traded near the critical 160 level against the dollar, reaching 159.81 on June 4 before fluctuating just above 160 on June 5 [1, 2].
Strong US employment data released on June 5 showed nonfarm payrolls increased by 172,000 in May, exceeding analysts’ expectations [2]. That boosted speculation that the Federal Reserve may raise interest rates again soon, impacting currency and stock markets. [2] Francesco Pesole, a currency strategist at ING, said, "It’s hard to argue against dollar strength at this juncture. Data continues to paint a picture of resilience for the US economy." [1]
Despite the strong jobs report, US stock markets faced steep declines. The Dow Jones Industrial Average dropped 695.15 points to 50,866.78, while the Nasdaq Composite Index fell 1,121.53 points to 25,709.43 on June 5 [2]. Asian markets also reacted negatively, with the Nikkei 225 futures plunging 3,750 points to 64,025 [2].
Geopolitical tensions added to market jitters. Iranian attacks on Kuwait on June 3 caused damage to the airport and injured dozens [1]. On June 4, Lebanon’s President Joseph Aoun announced that a ceasefire would come into effect within 24 hours once all parties approved [1].
The US dollar’s recent climb reflected a mix of economic strength signals and caution amid regional instability. Currency markets now watch for further US economic data and Fed announcements that may influence interest rate policy and exchange rates.
Markets remain volatile following the strong payroll figures and geopolitical updates as investors await the next Federal Reserve meeting, scheduled later in June.