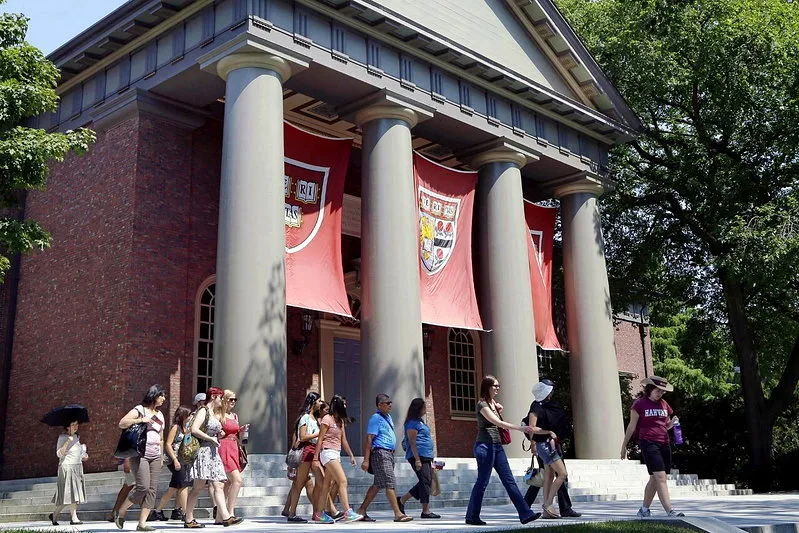
The US Treasury Department and IRS announced proposed regulations on September 3, 2026, that would strip federal tax-exempt status from private colleges and schools considering race in admissions, scholarships, or other educational policies [1, 2, 3, 4]. The proposal targets an estimated 18,000 private institutions across the country, including universities, trade schools, and elementary schools [1, 2, 3, 4].
The regulations would apply to taxable years beginning on or after May 31, 2027 [1, 2, 3, 4]. The rule covers admissions, educational policies, scholarships, loans, athletics, and all school-supported programs but exempts religious-based admissions [1, 2, 3, 4]. Schools using race-neutral criteria such as family income, hardship, or academic achievement to aid disadvantaged students would retain their tax-exempt status [1, 2, 4].
Treasury Secretary Scott Bessent said, "Schools rebranding race-based preferences as equitable, inclusive, or diversity-enhancing does not change their discriminatory nature" [4]. He added that "Today's Treasury and IRS proposed regulations establish a clear standard, and the institutions that continue to use discriminatory practices will no longer receive the benefits of federal tax-exempt status" [3]. IRS CEO Frank Bisignano said, "Private educational institutions that promote discriminatory practices will no longer be afforded the benefits of federal tax-exempt status" [3].
The proposal aligns with the 2023 Supreme Court ruling in Students for Fair Admissions, which barred race-conscious admissions policies [1, 4]. Legal experts have warned the approach may prompt lawsuits. Law professor Roger Colinvaux said, "This just opens the door for tax-exempt status to be weaponized... giving the IRS a tool to suppress speech or manipulate school behavior" [1].
Losing tax-exempt status could severely impact schools’ fundraising since donations would no longer be tax deductible [1, 3, 4]. The public comment period on the proposed regulations is expected to precede final rules ahead of the May 31, 2027 effective date [1, 2, 3, 4].